Myths About Registering a Company in India: 10 Facts
Myths About Registering a Company in India: 10 Myths Starting a business is exciting. However, the legal side of building a business can quickly become confusing, especially when founders receive different advice from friends, social media, consultants and other business owners. Some of the most common myths about registering a company relate to minimum capital, […]
Myths About Registering a Company in India: 10 Myths
Starting a business is exciting. However, the legal side of building a business can quickly become confusing, especially when founders receive different advice from friends, social media, consultants and other business owners.
Some of the most common myths about registering a company relate to minimum capital, GST, office space, company names, trademarks and ongoing compliance. A statement may sound simple, yet the actual legal position can depend on the type of business, its activities and the applicable rules.
This guide separates common misconceptions from the practical reality for Indian founders and small-business owners. The goal is not to suggest that every entrepreneur needs a Private Limited Company. Instead, it is to help you understand when company incorporation makes sense and what it does—and does not—do for your business.
What Does Registering a Company Actually Mean?
Before looking at individual myths, it helps to understand what company registration means. A company incorporated under the Companies Act, 2013 becomes a separate legal entity from its shareholders. It can enter contracts, own assets and conduct business in its own name, subject to applicable law.
A Private Limited Company is only one possible business structure. Depending on the founder’s needs, alternatives can include a Limited Liability Partnership (LLP), One Person Company (OPC), partnership firm or sole proprietorship.
For example, a founder planning to build a technology startup and raise equity investment may have different needs from a freelancer who is testing a small service business. Therefore, choosing the structure should come before assuming that incorporation is automatically necessary.
Lawizer’s Private Limited Company Registration service provides a starting point for founders considering incorporation.
Myth #1: You Must Register a Company Before Starting a Business
This is one of the most common misconceptions. Starting a business and incorporating a company are not the same thing.
Indian businesses can operate through different structures. A sole proprietorship, partnership, LLP and company each have different legal characteristics and compliance requirements.
Can You Run a Business Without Registering a Company?
In many cases, yes. A business does not automatically have to become a Private Limited Company simply because it wants to sell products or services.
However, this does not mean that an unincorporated business has no legal obligations. Depending on the activity, the business may need registrations, licences, tax registrations or local approvals.
- A freelancer may operate as a sole proprietor.
- Two or more professionals may consider an LLP or partnership.
- A scalable startup may consider a Private Limited Company.
- An eligible solo entrepreneur may consider an OPC.
Therefore, the better question is not simply, “Do I need a company?” Instead, ask, “Which business structure fits my current activity and future plans?”
For a detailed comparison, read Lawizer’s Private Limited vs LLP vs Sole Proprietorship guide.
Myth #2: An Unregistered Business Is Automatically Illegal
The word “unregistered” can create confusion because it can describe several different situations.
A business that is not incorporated as a company is not automatically illegal. For example, a sole proprietorship does not become a Private Limited Company simply because its owner starts selling goods or services.
At the same time, failing to obtain a registration that is actually required can create legal and financial problems. The correct requirements depend on the business activity, location, turnover and applicable law.
What Happens If a Company Is Not Registered?
If you intend to operate through a company, incorporation is what creates that company as a separate legal entity. Without incorporation, you cannot simply treat an informal business as though it were a Private Limited Company.
This distinction matters for contracts, ownership, banking, taxation and liability. It also matters when dealing with investors or institutional customers.
What Are the Legal Consequences of Having a Non-Registered Firm?
The answer depends on what “non-registered” means. A business may be legally operating under one structure while not having another registration that someone assumes is mandatory.
For example, company incorporation, GST registration, MSME registration and trademark registration are separate legal processes. One does not automatically replace the others.
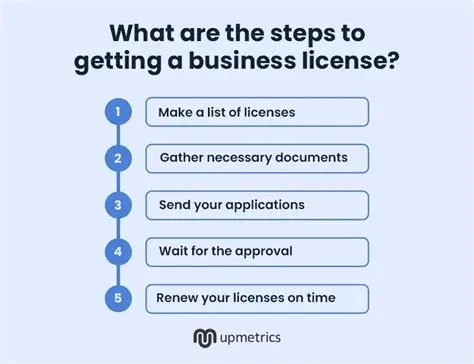
Lawizer’s guide to business licences and registrations for startups explains why founders should create a requirement-specific checklist instead of copying another business’s registrations.
Can a Third Party Sue an Unregistered Partnership Firm?
Yes, generally. The restrictions created by Section 69 of the Indian Partnership Act, 1932 mainly affect the ability of an unregistered firm or partner to institute certain suits to enforce contractual rights. They do not create a blanket rule that protects an unregistered partnership from being sued by outsiders.
Therefore, partnership registration should not be viewed as a shield against all legal claims. The precise position depends on the nature of the dispute and the right being enforced.
Can an Unregistered Partnership Firm Open a Bank Account?
Banking and registration are separate questions. Banks have their own KYC and documentation requirements, and an account may be available depending on the entity and documents provided.
However, founders should not confuse having a business bank account with having a separately incorporated legal entity.
What Are the Disadvantages of Not Registering a Partnership Firm?
For an unregistered partnership, one important concern is the restriction on bringing certain contractual claims under Section 69 of the Partnership Act.
There can also be practical disadvantages, such as weaker documentation, credibility concerns and difficulty proving the agreed business arrangement if the partners have relied mainly on informal promises.
Myth #3: You Need Huge Capital to Register a Company
Many first-time founders believe that incorporating a Private Limited Company requires them to deposit a large amount of money. That is not generally correct.
There is no general minimum paid-up capital requirement for incorporating an ordinary Private Limited Company. However, founders still need to decide the company’s authorised capital and initial subscription based on the proposed ownership and funding structure.
It is important to understand the difference between capital and registration costs. Government charges, stamp duty, Digital Signature Certificate costs and professional fees are separate from the company’s share capital.
For example, a founder should not assume that paying incorporation-related charges means that the same amount becomes the company’s share capital.
Capital planning also matters later. Changes to share capital can require additional corporate documentation and filings.
For a detailed explanation of incorporation documents and capital, see Lawizer’s Private Limited Company Registration guide.
You can also read the Private Limited Company Registration Cost guide to understand the different components of incorporation expenses.
Myth #4: Only Big Businesses Need Company Registration
Company incorporation is not reserved for large corporations. A small business can also choose a formal structure when that structure fits its goals.
For example, a startup expecting external investment may prefer a Private Limited Company even when its current revenue is small. The reason is not size alone. The structure can support share-based ownership and future investment.
On the other hand, a small professional business with two partners may prefer an LLP because its requirements and operating model may be different.
Therefore, founders should consider:
- Number of founders and owners.
- Personal liability concerns.
- Plans to raise equity investment.
- Expected growth and expansion.
- Compliance capacity.
- Tax and accounting considerations.
- Whether employees or investors will receive equity.
There is no single business structure that is perfect for every entrepreneur. Lawizer’s LLP Registration service and OPC Registration service can help founders compare alternatives to a Private Limited Company.
Myth #5: Company Registration Automatically Protects Your Brand
Registering a company name with the Ministry of Corporate Affairs and registering a trademark are two different things.
This distinction is extremely important for founders. A company name gives the entity its legal identity. A trademark, on the other hand, is concerned with protecting a brand or other qualifying mark under trademark law.
Is Company Name Registration the Same as Trademark Registration?
No. MCA name approval does not automatically give you comprehensive trademark rights over the brand.
A founder could therefore incorporate a company and later discover that a similar brand is already protected by another party. That is why checking the proposed name from both a company-law and trademark perspective is a sensible step.
Before investing heavily in a logo, website, packaging or marketing campaign, consider conducting an appropriate trademark search.
Lawizer provides Trademark Registration services for businesses looking to protect their brands.
You can also read Trademark Registration in India: Cost, Process and Timeline for a deeper explanation.
Myth #6: You Can Choose Any Company Name You Want
Founders have considerable freedom when choosing a business name. However, that freedom is not unlimited.
The proposed name must satisfy applicable company-name rules. It can also face issues if it is too similar to an existing company, LLP or protected trademark.
What Are the Rules for Naming a Company?
Before submitting a proposed name, founders should consider whether it is distinctive, legally acceptable and suitable for the proposed business activity.
A sensible name-checking process should consider:
- Existing company and LLP names.
- Existing trademarks.
- Restricted or regulated expressions.
- Potentially misleading words.
- Similarity with well-known brands.
- Whether the name accurately reflects the proposed business.
What Words Are Not Allowed in Company Names in India?
There is no short universal list that can safely be applied to every proposed name. Certain expressions may be restricted, inappropriate or subject to additional requirements depending on their use and context.
Therefore, instead of relying on a social-media list of “banned words”, founders should check the current MCA naming rules when preparing the incorporation application.
What Should You Avoid When Naming a Company?
- Names that are confusingly similar to existing entities.
- Names that may conflict with existing trademarks.
- Names that falsely suggest government affiliation.
- Names that make misleading claims about the business.
- Names that unnecessarily restrict future expansion.
Choosing a name carefully at the beginning can save time and reduce the risk of having to rethink your branding later.
Myth #7: You Need an Expensive Commercial Office to Register a Company
Another common misconception is that a founder must rent a large commercial office before incorporating a company.
In reality, what matters is having a valid registered office that satisfies the applicable legal requirements. A commercial office is not automatically required simply because the business is a Private Limited Company.
Depending on the circumstances, a residential or rented premises may be used as the registered office if the required documentation and conditions are satisfied.
Typical documents can include appropriate address proof, ownership or possession documents, a rent or lease agreement and an owner’s no-objection certificate where applicable.
Lawizer’s Company Registration Documents Checklist explains the documents founders should prepare before incorporation.
For Kolkata and West Bengal founders, Lawizer also provides a guide to registering a startup in Kolkata and West Bengal.
Myth #8: Company Registration Automatically Means GST Registration
Company incorporation and GST registration are separate processes.
Incorporating a Private Limited Company does not, by itself, mean that GST registration is automatically required in every case. GST applicability depends on factors such as the nature of supplies, aggregate turnover, location and specific compulsory-registration provisions.
For example, a founder should not simply copy the GST registration status of another company and assume that the same rule applies to their business.
When Should a Founder Check GST Registration?
A founder should assess GST requirements before beginning taxable business activity and whenever there is a significant change in turnover, business model, location or type of supply.
Particular attention may be needed where the business makes supplies or transactions that fall under compulsory-registration provisions.
Because GST rules and notifications can change, founders should check the current position rather than relying on an old turnover figure found online.
Lawizer’s GST Registration service can be used alongside the more detailed GST Registration for Startups guide.
Myth #9: Once the Company Is Registered, the Legal Work Is Finished
This is perhaps the most expensive misconception for a new founder.
Incorporation creates the company. It does not remove the company’s future statutory, tax and regulatory responsibilities.
After incorporation, a company may need to deal with matters such as corporate records, accounting, applicable tax registrations, commencement-related requirements, annual filings and event-based filings.
What Happens After Company Registration?
The exact requirements depend on the company and its activities. However, founders should generally create a post-incorporation checklist covering:
- Corporate bank-account arrangements.
- Share capital and initial corporate records.
- Applicable commencement-of-business requirements.
- GST and other tax registrations, where applicable.
- Accounting and financial records.
- Annual MCA/ROC compliance.
- Income-tax compliance.
- Director-related filings and requirements.
- Industry-specific licences and registrations.
For example, missing recurring ROC filings can lead to additional fees and compliance problems. Therefore, founders should think about compliance from the beginning rather than waiting until the first deadline approaches.
Lawizer’s Annual Compliance service can help businesses understand recurring compliance requirements.
You can also read What Happens If You Miss Your ROC Annual Filing Deadline? to understand why timely filings matter.
Myth #10: Company Registration Is Too Complicated to Complete Online
Company incorporation in India involves several documents and declarations. However, the process is substantially digital.
The MCA’s prescribed incorporation system allows founders to submit the required information electronically. Depending on the company, the process can involve Digital Signature Certificates, director information, registered-office documents, constitutional documents and other linked requirements.
Can a Founder Register a Private Limited Company Online?
Yes. Much of the process can be handled online. However, “online” does not mean “no legal formalities”. The quality of the documents and accuracy of the information still matter.
Common causes of delays include:
- Incorrect names or spellings.
- Mismatched address details.
- Incomplete identity documents.
- Problems with registered-office documentation.
- Errors in the proposed business objects.
- Incorrect or incomplete declarations.
Therefore, preparing the documents before filing can make the process much smoother.
Read Lawizer’s Private Limited Company Registration guide for a detailed overview of the incorporation process.
Bonus Myth: Registering a Company Automatically Makes It a Startup
Incorporating a company and receiving official startup recognition are not necessarily the same thing.
DPIIT startup recognition under the Startup India framework has its own eligibility requirements. Current Startup India guidance includes eligible Private Limited Companies, registered partnership firms, LLPs and certain cooperative entities within the recognition framework, subject to the applicable conditions. :contentReference[oaicite:1]{index=1}
Therefore, a newly incorporated company should not assume that incorporation alone automatically gives it every Startup India benefit.
Recognition and specific benefits can have separate eligibility conditions. For example, Section 80-IAC tax exemption has its own requirements beyond simply having a new company. :contentReference[oaicite:2]{index=2}
Founders interested in this route can explore Lawizer’s Startup India Registration assistance.
10 Myths About Registering a Company: Myth vs Reality
| Myth | Reality |
|---|---|
| You must register a company before starting any business. | Different businesses can operate through different legal structures. |
| An unregistered business is automatically illegal. | The legal position depends on the structure and applicable requirements. |
| You need huge capital to incorporate. | There is no general minimum paid-up capital requirement for an ordinary Private Limited Company. |
| Only large businesses need formal structures. | Small businesses may also choose formal structures based on their goals. |
| Company registration protects your brand. | Company incorporation and trademark registration are separate. |
| You can choose any company name. | Proposed names must satisfy applicable legal and naming requirements. |
| You need an expensive commercial office. | You need a valid registered-office arrangement, not necessarily a premium office. |
| Company incorporation automatically means GST registration. | GST applicability depends on the relevant GST rules and the business’s circumstances. |
| There is nothing to do after incorporation. | Companies have continuing corporate, tax and regulatory obligations. |
| Company incorporation is too complicated to do online. | The incorporation process is substantially digital, although documentation and legal formalities still matter. |
How to Avoid Common Company Registration Mistakes
Understanding the myths is useful, but founders also need a practical checklist. Before registering a business, take the following steps.
- Choose the right structure. Compare a Private Limited Company, LLP, OPC, partnership or proprietorship based on your actual needs.
- Decide the ownership structure. Agree on founder contributions and ownership before filing.
- Check the proposed name. Review both company-name availability and potential trademark conflicts.
- Prepare your documents. Keep identity, address and registered-office documents ready.
- Understand GST applicability. Do not assume incorporation automatically creates a GST obligation.
- Review industry licences. Some sectors have additional approvals.
- Protect the brand. Consider trademark registration where appropriate.
- Document founder relationships. A written Co-Founder Agreement can clarify roles, ownership, responsibilities and exit arrangements.
- Plan for future shareholders. Where relevant, understand how a Shareholder Subscription Agreement or shareholders’ agreement may fit into future fundraising.
- Plan compliance from Day One. Incorporation should be followed by a clear compliance calendar.
Lawizer’s Legal List for New Founders is another useful resource for organising these early legal steps.
Frequently Asked Questions About Company Registration Myths
1) What Are the Top 10 Myths About Registering a Company?
The most common myths are that every business must incorporate, incorporation requires huge capital, a commercial office is mandatory, company registration protects a trademark, GST automatically becomes mandatory, any company name can be chosen, and compliance ends after incorporation. In reality, each issue depends on the business structure and applicable law.
2) What Are 5 Examples of Myths About Company Registration?
- Every business must become a Private Limited Company.
- A founder needs a large amount of capital to incorporate.
- A company must have an expensive commercial office.
- Company incorporation automatically protects the brand name.
- There are no legal obligations after incorporation.
3) What Is the Biggest Myth About Registering a Company?
One of the biggest misconceptions is that company incorporation is the same as business registration in general. In reality, India has several business structures, and each has its own legal and compliance framework.
4) Can You Run a Business Without Registering a Company?
Yes, depending on the business and its legal requirements. A sole proprietorship or partnership, for example, is different from an incorporated company. However, the business may still need GST, local, sector-specific or other registrations depending on its activities.
5) What Happens If a Company Is Not Registered?
If you intend to operate through a company, incorporation is required to create that company as a separate legal entity. If you instead operate through another lawful structure, the business will be governed by the rules applicable to that structure.
6) What Are the Legal Consequences of Having a Non-Registered Firm?
The consequences depend on the structure and the registration being discussed. For example, an unregistered partnership can face restrictions under Section 69 of the Indian Partnership Act when attempting to enforce certain contractual rights. Other registrations have different rules.
7) Can a Third Party Sue an Unregistered Partnership Firm?
Yes, generally. The restrictions under Section 69 mainly concern suits brought by an unregistered firm or partner to enforce certain contractual rights. They do not provide blanket immunity from claims brought by third parties.
8) Can an Unregistered Partnership Firm Open a Bank Account?
Possibly, depending on the bank’s KYC and documentation requirements. However, a business bank account should not be confused with incorporation as a separate legal entity.
9) What Are the Disadvantages of Not Registering a Partnership Firm?
An important disadvantage is the restriction on certain contractual suits under Section 69 of the Partnership Act. Informal arrangements can also create practical problems when partners disagree about ownership, contributions or responsibilities.
10) What Are the Rules for Naming a Company?
The proposed name must comply with applicable MCA requirements and should not create prohibited or confusing similarities with existing entities. Founders should also check trademark conflicts before committing to a brand.
11) What Words Are Not Allowed in Company Names in India?
There is no single short list that safely covers every situation. Certain words or expressions may be restricted or may require additional approvals. The current MCA naming rules should be checked before submitting the proposed name.
12) What Should You Avoid When Naming a Company?
Avoid names that are confusingly similar to existing entities, conflict with trademarks, falsely imply government affiliation or make misleading claims about the business.
13) Can AI Create a Business Name?
Yes. AI can be useful for generating creative business-name ideas. However, an AI-generated name is not automatically legally available. Before adopting it, check company-name availability and potential trademark conflicts.
14) What Is the Luckiest Business Name?
There is no universally recognised “luckiest” business name under company law. From a business perspective, a strong name should be distinctive, memorable, suitable for the brand and legally available.
15) What Are Some Fake Business Names?
Rather than using real businesses as examples, consider generic names such as “Government India Finance Services” or “National Authority Consulting” where the wording falsely suggests a government connection. The broader lesson is to avoid names that could mislead customers about who operates the business.
16) What Are the Four Main Types of Entrepreneurs?
There is no single legally prescribed list of four entrepreneur types. Common business textbooks may classify entrepreneurs as innovative, imitative, Fabian and drone entrepreneurs. These are educational classifications, not legal business structures.
17) What Are the 7 Ms of Entrepreneurship?
The “7 Ms” is an entrepreneurship framework rather than a statutory company-registration requirement. Different textbooks use slightly different versions. It is generally used to discuss business resources and management rather than legal incorporation.
18) What Are the 4 Ms of Entrepreneurship?
The “4 Ms” is another business-management framework. Depending on the source, it can refer to different groups of business resources. Founders should therefore check the specific textbook or course context rather than treating it as an official legal requirement.
19) What Are the Four Cs of Entrepreneurship?
The Four Cs is also a business concept rather than a company-law rule. Different entrepreneurship frameworks use the term differently, so the meaning should be understood in the context in which it is being taught.
20) What Are the 12 Different Types of Entrepreneurs?
There is no universally accepted legal list of twelve entrepreneur types. Different business and entrepreneurship resources use different classifications. These classifications describe entrepreneurial styles; they do not determine whether someone should register a Private Limited Company, LLP or another entity.
Final Takeaway: Do Not Let Myths Decide Your Business Structure
Company registration is an important step, but it should not be driven by assumptions. A business does not become better simply because it chooses the most formal structure. The right structure is the one that fits its ownership, liability, funding plans, operations and long-term goals.
Similarly, incorporation is not the same as GST registration, trademark protection, MSME registration or startup recognition. These are separate areas that may become relevant at different stages.
Most importantly, the legal work does not necessarily end when the Certificate of Incorporation arrives. Ongoing corporate, tax and regulatory compliance should be planned from the beginning.
If you are unsure whether your business should be a Private Limited Company, LLP, OPC or another structure, start by understanding your actual requirements. You can then build the appropriate registration and compliance checklist around them.
Lawizer provides Startup & Business Legal Services covering company incorporation, LLP registration, GST, Startup India, MSME, trademark protection and related business documentation.
Need help deciding what your business actually needs? Consult Lawizer before you register so that your business structure, documentation and compliance plan are aligned from the beginning.